Module 1 / 2
VWAP bounce – the first pullback to the mean
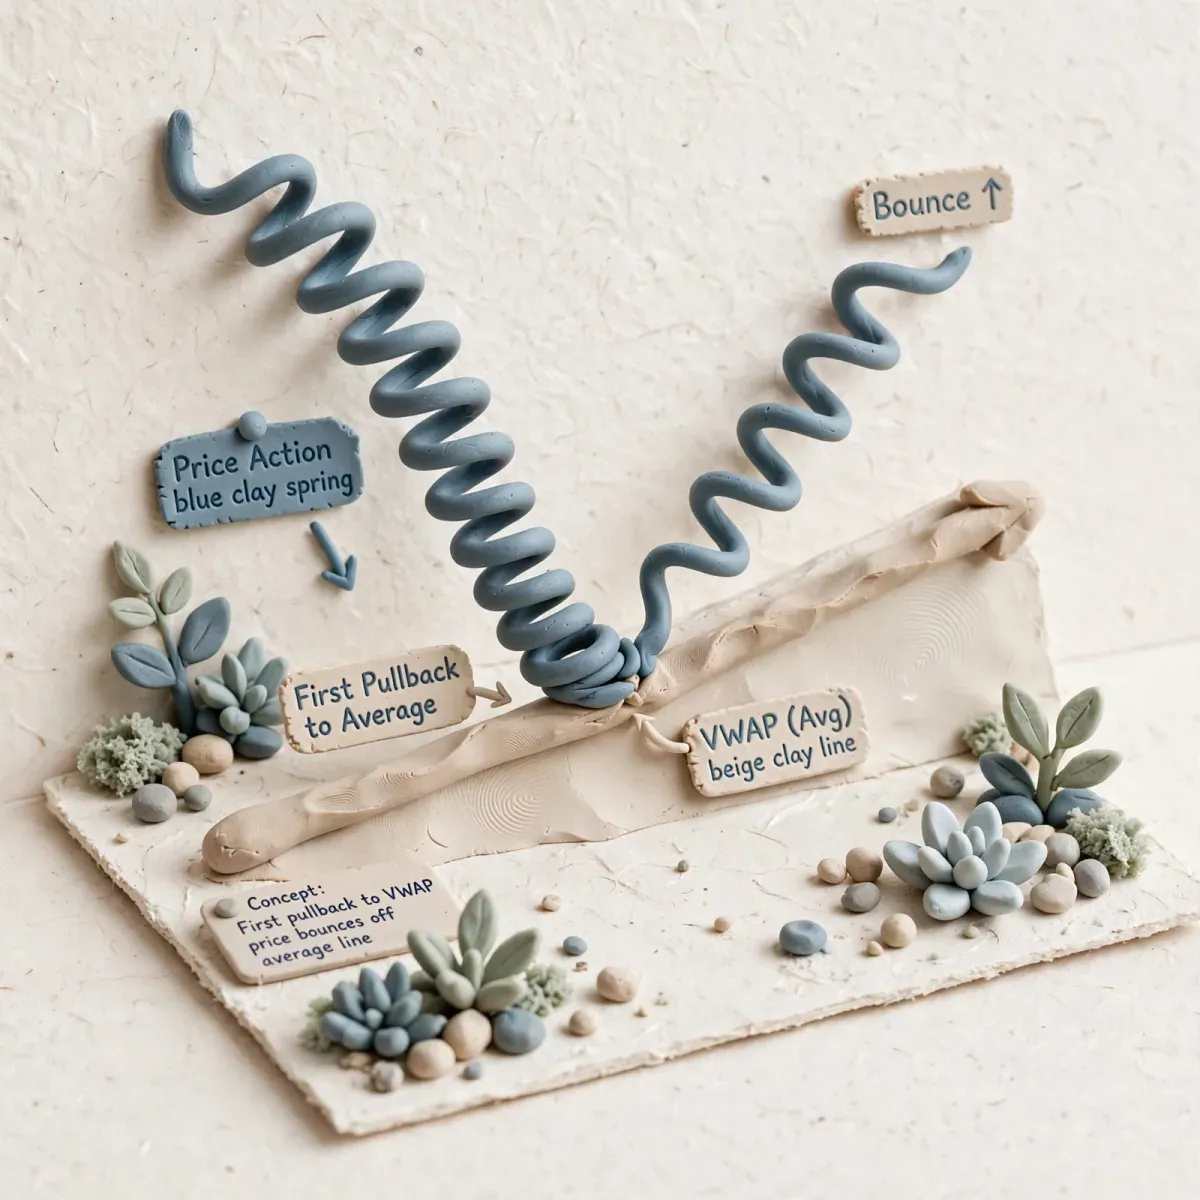
VWAP – Volume Weighted Average Price – is the average price weighted by volume from the start of the session. For a day trader it is the reference line…
- Author
- Zordon Intelligence Sp. z o.o.
- Updated
- 5 min read
- Structure sources
- 2
VWAP – Volume Weighted Average Price – is the average price weighted by volume from the start of the session. For a day trader it is the reference line for the intraday supply/demand side. The “first pullback to VWAP” system plays the return to the mean after the opening impulse, but only the first time VWAP is tested.
Lesson goal
- Calculate and interpret VWAP, deviations and bands.
- Define the first pullback setup: impulse, pullback, rejection signal.
- Tell a tradeable bounce apart from a trend run without a pullback.
- Build a management plan with a hard invalidation.
VWAP – the foundation
VWAP = sum( Price_typical * Volume ) / sum( Volume )
Price_typical = (High + Low + Close) / 3

Band_k = VWAP +/- k * stdev( Price_typical - VWAP )   where k=1,2

VWAP slope:
Slope = (VWAP_now - VWAP_N_bars_ago) / N
Slope > 0 = buyers' session, <0 = sellers'
For a day trader: rising VWAP + price above VWAP = look for a long on the pullback. Falling VWAP + price below VWAP = a short on the pullback. Flat VWAP = rotation.
Structure of the 1st pullback setup
Phase 1 – Impulse: a strong move from the open, price moves away >0.8-1.0 std from VWAP, rising volume.
Phase 2 – Pullback: price comes back towards VWAP, falling volume, candles with smaller bodies, 3-7 bars of 1m.
Phase 3 – Bounce: rejection around VWAP (+/- 0.1-0.2 std). Signal: a hammer, an engulfing candle, no close below VWAP on the 1m, rising volume on the bounce.
| Element | Long | Short |
|---|---|---|
| VWAP slope | >0, rising for min 15 min | <0, falling for min 15 min |
| Price position | Price > VWAP for the whole impulse | Price < VWAP for the whole impulse |
| Pullback | A move down to VWAP +/- band 0.2, does not close < VWAP -0.2std | A move up to VWAP, does not close > VWAP+0.2std |
| Trigger | 1m close above VWAP + volume > avg | 1m close below VWAP + volume > avg |
| Stop | 0.3*ATR below the pullback low or below VWAP-0.5std | The reverse |
Quality filters
- First pullback only: the second and third test of VWAP have a much lower success rate.
- Time: best 9:45-11:30 ET / 9:30-11:30 CET. In the afternoon VWAP is smoothed out.
- Impulse distance: if the impulse was <0.5 ATR, the pullback is rotation, not a setup.
- Anchored VWAP: for gaps also use an AVWAP anchored to the pre-market high or to the open.
Management and targets
Stop = pullback low - 0.2*ATR 5m  (long)
Target 1 = impulse high (re-test)
Target 2 = 1.5 * impulse or a 1*ATR extension
Minimum RR = 1.5
Invalidation rule: a 5m close on the opposite side of VWAP by >0.3std = the setup is over
Measuring the setup
Keep a journal:
Date | Gap | VWAP slope | Impulse distance std | 1st pullback? | Result R | Holding timeThe difference between VWAP and SMA and why it matters
SMA counts prices equally. VWAP weights them by volume – it shows where the most transactions actually went through. That is why institutions use VWAP as an execution benchmark. If funds buy and their avg is worse than VWAP – they underperform. That forces them to trade near VWAP, which creates your bounces.
A numerical VWAP example
Session: 9:30 open 100, 9:31 high 101 vol 100k, 9:32 low 99.8 vol 200k
VWAP shifts closer to 100.2 because the volume is larger there.
First impulse to 101.5 (1.3 ATR above VWAP), pullback 5 bars to 100.3 (= VWAP 100.25 + 0.05)
Long trigger: 1m close 100.45, bounce volume 150% of the 5-bar avg.
Stop 100.0 (swing - 0.2 ATR), target 101.5
RR = (101.5-100.45)/(100.45-100.0)=1.05/0.45=2.33
Multi-timeframe VWAP
Use two VWAPs:
- The session VWAP (from 9:30 ET) – the main one
- An AVWAP anchored to the day low / PM low – for the trend When both rise and slope >0 – a long filter. When they diverge in direction – rotation.
Managing a losing bounce
A bounce that does not move >0.2 ATR within 3 minutes is weak. Rule: if after the trigger price does not make 0.5R in 3 min, close 50%. You eliminate bagholders and free up capital.
When the plan says DO NOT TRADE
- Flat VWAP (slope ~0 for 30 min).
- The pullback is the 5th test of VWAP that day.
- Price has already crossed VWAP 6+ times today – a rotational day.
- Spread + slippage > 20% of your stop.
- News in <5 minutes.
- No impulse before the pullback – not every touch of VWAP is a setup.
The mistakes that cost the most
- Catching a knife: entering in the middle of the pullback, before the rejection signal.
- Averaging down under VWAP: I will add if it goes lower – a VWAP bounce requires cutting.
- Trading against the slope: long while VWAP is falling, because it is “cheap”.
- A stop that is too wide: a 2ATR stop on M1 with a 0.5ATR target – RR <1.
- Confusing the session VWAP with an AVWAP from D1.
Measurable exercise (90 minutes)
- Take the last 10 sessions of one instrument with a clear open trend.
- Mark the first pullback to VWAP on each day.
- For each one: measure the impulse in std of VWAP and in ATR, the pullback duration, and the result if you had entered on the 1m close after the rejection with a 0.3 ATR stop.
- Count: how many of the 10 were tradeable? WinRate? AvgR?
- Add the filter slope >0 for at least 15 min.
The task ends with a table of 10 rows + a conclusion.
Test yourself
- Price 2 std above VWAP, rising slope, a pullback of 4 bars of 1m to VWAP + a hammer on rising volume. Does this meet the criteria for a 1st pullback long?
- Why is the second and third test of VWAP statistically weaker than the first?
- How do you calculate the buffer for the entry so that you do not enter on every touch?
- What invalidates a long setup on VWAP?
Frequently asked questions
Does VWAP work on 1 min? Yes, provided there is volume. On low volume it is choppy. Compare the 1m and 5m VWAP.
AVWAP or the plain VWAP? The session one – the basis. AVWAP to PM_H, PD_H – as an additional filter.
Should you trade a bounce when price is 3 std from VWAP? No. That is an extension. Wait for the impulse -> pullback.
Which stop is best? The pullback swing +/- a 0.2 ATR buffer.
VWAP is a statistical tool showing the average transaction price of the day. It is not a magic support line. It needs the context of slope, volume and time.
Advertisement
Key takeaways
- VWAP – Volume Weighted Average Price – is the average price weighted by volume from the start of the session. For a day trader it is the reference line for the intraday supply/demand side. The "first pullback to VWAP" system plays the return to the mean after the opening impulse, but only the first time VWAP is tested.
Structure sources
The material is based on source documents. Variable values — fees, limits, regulatory figures — are worth checking at the source before making a decision.
- Babypips — School of Pipsology — babypips.com
- TradingView — Pine Script documentation
Disclaimer
- Educational material. Not investment advice or a recommendation. Trading involves the risk of losing capital.
- The materials are educational. They are not investment advice or a recommendation within the meaning of financial instruments trading regulations. Numbers in examples are illustrative unless a measurement date and source are given.
Who writes this and how we check it
The materials are written and verified by Redakcja Kurs Tradera — the rules are described on about the site: every number has a source, and we show gaps openly. Report a factual error via contact — corrections are described in the content.
Progress is stored only in this browser (localStorage) — there is no account and no copy on the server. Clearing site data will remove it. Manage your data