Module 2 / 2
Glossary and mechanics - M0, M1, M2, QE, QT, base, multiplier
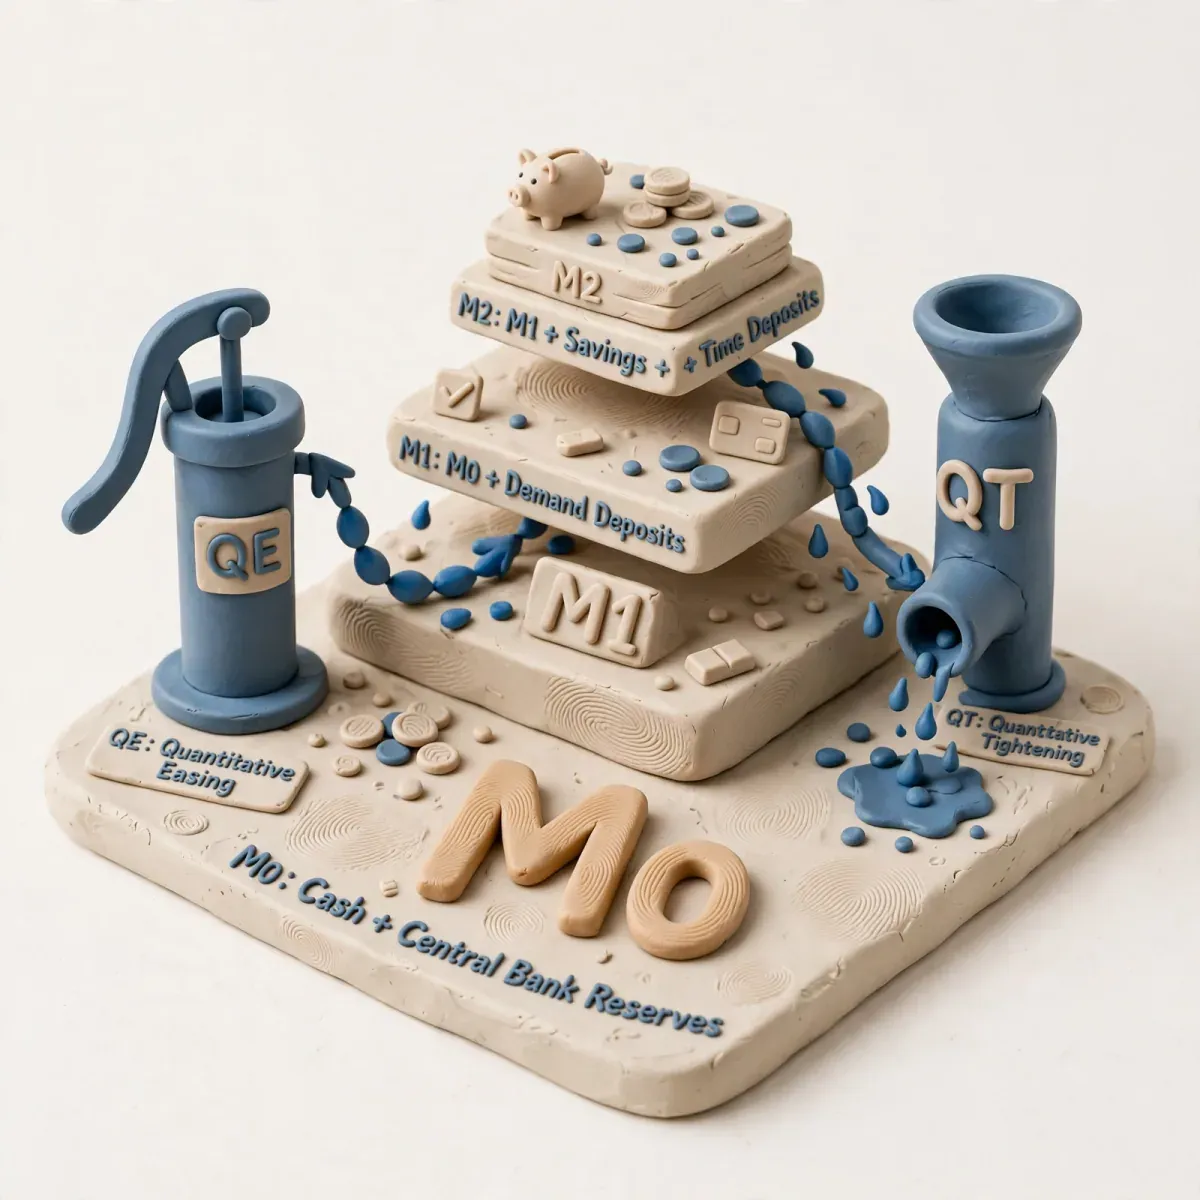
This lesson is a toolbox. Without the definitions of M0, M1, M2, QE, QT, the monetary base, the multiplier, and repo, you are monetarily illiterate. With them, you read the Fed balance sheet like a company balance sheet. It is a dictionary lesson, but with mechanics, not dry definitions. Every term comes with a formula, a Polish example...
- Author
- Zordon Intelligence Sp. z o.o.
- Updated
- 9 min read
- Structure sources
- 2
This lesson is a toolbox. Without the definitions of M0, M1, M2, QE, QT, the monetary base, the multiplier, and repo, you are monetarily illiterate. With them, you read the Fed balance sheet like a company balance sheet. It is a dictionary lesson, but with mechanics, not dry definitions. Every term comes with a formula, a Polish example, and a trap for the trader.
Money - layers like an onion
Picture three circles:
Circle 0 - Monetary base (M0, Base Money, High-powered money):
M0 = Currency in circulation (outside banks) + Bank reserves at the central bank

PL, May 2024: Currency ~380 bn PLN + Reserves ~100 bn = M0 ~480 bn
US: Currency 2.3 trn USD + Reserves 3.3 trn = M0 5.6 trn
It is the only money created directly by the central bank. Everything else is derived from it.
Circle 1 - M1 (narrow transaction money):
M1 = Currency in circulation + Demand deposits (at call, overnight)

PL: M1 ~1.6 trn PLN (2024)
US: M1 ~18 trn USD (after the 2020 redefinition - it now includes savings deposits)
This is what you pay with instantly. Liquid.
Circle 2 - M2, M3 (broad money):
M2 = M1 + Time deposits up to 2 years + Deposits redeemable at up to 3 months' notice
M3 = M2 + Debt securities up to 2 years + repo operations + money market funds

The NBP in PL reports mainly M3: ~2.3 trn PLN (2024)
M3 is the best measure of credit in the economy.
The money creation multiplier:
Multiplier = M3 / M0

PL: 2.3 trn / 0.48 trn = 4.8x
US: 21 trn / 5.6 trn = 3.75x
Euro area: 16 trn / 6 trn = 2.7x

The higher the multiplier, the more credit per 1 PLN of base. In 2007 in PL it was 6.5x - a mortgage boom.
QE, QT, repo, reverse repo - the mechanics
QE - quantitative easing:
Step 1: The central bank announces it will buy 100 bn of government bonds
Step 2: A commercial bank sells bonds to the central bank
Step 3: The central bank books it: Assets +100 bn of bonds, Liabilities +100 bn of the bank's reserves
Step 4: Reserves = liquidity. The bank can use them for settlements; it does not have to lend them out right away.

Effect: Bond yields fall (because of the demand), bond prices rise, the cost of long-term credit falls.
Types of QE: QE1 (MBS), QE2 (Treasuries), QE3 (open-ended).
QT - quantitative tightening:
The central bank does not reinvest maturing bonds.
A 10 bn bond matures; the State Treasury repays the central bank from its account at the central bank (TGA).
Bank reserves fall by 10 bn. Base money disappears.

The Fed's QT pace in 2023-24: 60 bn Treasuries + 35 bn MBS per month = 95 bn/month.
QT is a drain on liquidity. In 2019 QT plus an oversized TGA caused the repo crisis and the Fed had to go back to QE (repo QE).
Repo and Reverse Repo:
Repo: A bank borrows cash against bonds as collateral for 1 day. Repo rates = the cost of secured money.
Reverse repo (RRP): Funds lend cash to the central bank and receive a bond as collateral. It is the vacuum cleaner for excess liquidity.

US RRP at its 2022-23 peak: 2.5 trn USD - that much excess cash sat at the Fed, because banks did not want the deposits (regulation).
When RRP falls, liquidity returns to the market (the 2023-24 rally was partly driven by this).
TGA - Treasury General Account: The US government’s account at the Fed. When TGA rises (taxes), reserves fall (less liquidity). When TGA falls (the government spends), reserves rise (more liquidity). That is why equity traders watch TGA as a liquidity indicator.
Fed_net_liquidity = Reserves + RRP

L. Caldas formula: Liquidity = Fed balance sheet - TGA - RRP

When liquidity rises -> a tailwind for stocks.
When it falls -> a headwind.
Rates - which one is which?
| Rate | What is it? | Who sets it? | What do you use it for? |
|---|---|---|---|
| NBP reference rate / Fed funds | The rate on an overnight loan between banks, the central bank’s target | The Monetary Policy Council (RPP) / FOMC | The anchor for the whole system |
| WIBOR / SOFR / €STR | The market interbank rate at which banks actually lend | The market, a fixing | The price of a mortgage and of corporate loans |
| 10Y yield (PL 10Y, US 10Y) | The yield on a 10-year bond | The bond market | The discount rate for stocks, the cost of government debt |
| Real rate = nominal - expected inflation | What you really earn after inflation | Calculated | Deciding whether to hold bonds vs stocks vs gold |
| OIS, FRA | Swaps on future rates | The market | Expectations about future central bank decisions |
The Fisher equation:
(1 + nominal) = (1 + real)*(1 + expected inflation)
Approximately: real ~ nominal - expected inflation

Example: US 10Y 4.2% - expected 5y5y inflation 2.3% = real 1.9%
If the real rate is >2%, growth stocks suffer.
The monetary trader’s MUST-HAVE glossary
Monetary base / M0: Currency + reserves. Only the central bank creates it.
Money multiplier: M3/M0. It tells you how much credit there is per 1 unit of base.
Velocity (V): MV=PQ. How fast money circulates. It falls in a crisis.
LCR, NSFR, CET1: Bank regulatory ratios. LCR - whether you have liquid assets for 30 days of outflows. CET1 - the highest-quality capital / risk-weighted assets. If <10%, the bank is thin.
Bail-in vs Bail-out: Bail-out - the taxpayer rescues the bank. Bail-in - creditors and depositors above 100k EUR rescue the bank internally (Cyprus 2013, the BRRD directive in the EU since 2016).
Yield Curve Control (YCC): The central bank promises to keep a yield, for example the 10Y, at 0% for as long as it takes by buying without limit (Japan until 2023). The end of YCC in Japan is a major regime shift.
Forward Guidance: A verbal promise about future rates. It comes in 3 kinds: calendar-based (“until the end of 2025”), state-based (“as long as unemployment is >6.5%”), and Delphic (a forecast).
Open market operations: Buying/selling short-term securities to keep the overnight rate close to target.
Trap table - what confuses beginners
| Media term | What the media say | What it really means | The trap |
|---|---|---|---|
| “The Fed printed 5 trn” | Cash is falling from helicopters | It swapped bonds for reserves, M0 rose, but M3 depends on credit | M0 != the money in your pocket |
| “Inflation is falling so things are cheaper” | Prices are falling | Disinflation - prices rise more slowly, the level is still higher | The basket is still +30% vs 2020 |
| “The NBP has 190 bn in reserves, so the PLN is safe” | That is a lot, so it will not collapse | Reserves cover ~6 months of imports plus defending the exchange rate for weeks, not years | With outflows of 10 bn/month they last 19 months, but at the cost of confidence |
| “The bank is profitable, so it is safe” | Profit = safe | Book profit can come from revaluing bonds that later fall | SVB was profitable a month before it failed |
When the plan says: do not trade
- When you do not know whether you are looking at M0, M1 or M3. Commenting that “supply is rising” without saying which M is fortune-telling. A professional says: PL M3 +7% y/y, M0 +2% - that is bank credit expansion, not the NBP.
- When you confuse the nominal rate with the real one. A 6% bond with 11% inflation is -5% in real terms. A stock at a P/E of 15 with a real rate of -5% is an opportunity. With a real rate of +3% it is expensive. Without the real rate you cannot judge it.
- When you trade on the day of a CPI/PCE release without a plan for the revision. The first reading is a flash estimate, then comes the revision. In 2023 the US CPI was revised 3 times. Algos trade the first second, you trade the interpretation 10 minutes later.
The mistakes that cost the most
Mistake 1: Treating M0 as a measure of future inflation. The correlation of M0 -> CPI in the US from 2008 to 2020 was close to zero. The correlation of M2 -> CPI with a lag of 12-18 months was 0.7 in 2021-23. Measure the right M.
Mistake 2: Ignoring TGA and RRP when analysing US liquidity. In 2023 the Fed was doing QT (-95 bn/month), but TGA was falling by -150 bn/month. Net liquidity rose despite QT, so the S&P 500 rose. A trader looking only at QT shorted and lost.
Mistake 3: Not understanding that WIBOR is not the NBP rate. The NBP rate is 5.75%, WIBOR is 6.2% = a 45bp margin for interbank credit risk and liquidity. In a crisis the margin widens to 100-200bp, so a mortgage gets more expensive even though the NBP is not hiking. In 2008, WIBOR - the NBP rate = +200bp.
A measurable exercise
Goal: Build your own monetary monitor for PL and the US.
Steps:
- Create a spreadsheet with these columns:
| Date | M0 PL | M3 PL | Multiplier | M0 US | M3 US | Fed balance sheet | TGA | RRP | Net liquidity (Fed - TGA - RRP) | WIBOR 3M | Real PL rate (WIBOR - CPI) |
|---|
- Download monthly data: the NBP - money supply, FRED (FRED series: BOGMBASE, M2SL, WALCL, WTREGEN, RRPONTSYDH).
- Calculate monthly and 12-month percentage changes.
- Ask the question: when Fed net liquidity rises 2% m/m, what does the S&P 500 do over the following month? Calculate the correlation over 24 months.
- Write down a rule: “When net liquidity falls 3 months in a row, I cut my stock exposure by X%” - that is a simple, measurable regime filter.
Test yourself
- Define M0, M1 and M3 using PLN as the example and give the value of the M3/M0 multiplier for PL. What does a high multiplier mean?
- Explain the difference between QE and plain cash printing. What appears in the assets and liabilities of the central bank during 100 bn of QE?
- What are repo and reverse repo? Why did an RRP of 2.5 trn in the US mean excess liquidity?
- Calculate the real interest rate: WIBOR 6% - expected inflation 4%, and interpret it for growth stocks versus value stocks.
- Explain the formula: Liquidity = Fed balance sheet - TGA - RRP. Why is a fall in TGA bullish for stocks in the short term?
Frequently asked questions
Why did M1 in the US explode in 2020? Because the Fed changed the definition in May 2020 - savings accounts began to count as transaction accounts in M1. That is why M1 jumped from 4 trn to 18 trn overnight, with no printing. It shows how definitions ruin comparisons.
What is sterilisation? When a central bank buys assets (QE) and at the same time sells others so as not to increase the base. For example, the ECB bought Italian bonds but sold German bills. Rarely used now.
Does the NBP do QE? Yes - in 2020-2021 the NBP bought about 150 bn PLN of bonds (structural open market operations). It was not officially called QE, but the mechanics were the same. It bought government bonds and bonds guaranteed by the State Treasury (PFR, BGK).
What is the difference between a yield and an interest rate? An interest rate is the price set by the central bank or the interbank market for short money. A yield is the return the market demands for lending to the government for a long time (for example 10 years), taking into account expected future rates plus a risk premium. The yield comes from rates, but it contains expectations.
Advertisement
Key takeaways
- This lesson is a toolbox. Without the definitions of M0, M1, M2, QE, QT, the monetary base, the multiplier, and repo, you are monetarily illiterate. With them, you read the Fed balance sheet like a company balance sheet. It is a dictionary lesson, but with mechanics, not dry definitions. Every term comes with a formula, a Polish example...
Structure sources
The material is based on source documents. Variable values — fees, limits, regulatory figures — are worth checking at the source before making a decision.
- Central banks — publications from the Fed, the ECB, and Poland's central bank (NBP) — nbp.pl
- BIS — annual economic reports
Disclaimer
- Educational material. Not investment advice or a recommendation. Trading involves the risk of losing capital.
- The materials are educational. They are not investment advice or a recommendation within the meaning of financial instruments trading regulations. Numbers in examples are illustrative unless a measurement date and source are given.
Who writes this and how we check it
The materials are written and verified by Redakcja Kurs Tradera — the rules are described on about the site: every number has a source, and we show gaps openly. Report a factual error via contact — corrections are described in the content.
Progress is stored only in this browser (localStorage) — there is no account and no copy on the server. Clearing site data will remove it. Manage your data