Module 2 / 2
POC-to-POC strategies - trading value without guessing
You have all the building blocks: Volume Profile, TPO, Footprint, Delta, DOM. Now you will combine them into measurable strategies. Professional value trading is not guessing whether price will bounce. It is playing the move statistically from one place where value is built to another.
- Author
- Zordon Intelligence Sp. z o.o.
- Updated
- 8 min read
- Structure sources
- 2
You have all the building blocks: Volume Profile, TPO, Footprint, Delta, DOM. Now you will combine them into measurable strategies. Professional value trading is not guessing whether price will bounce. It is playing the move statistically from one place where value is built to another.
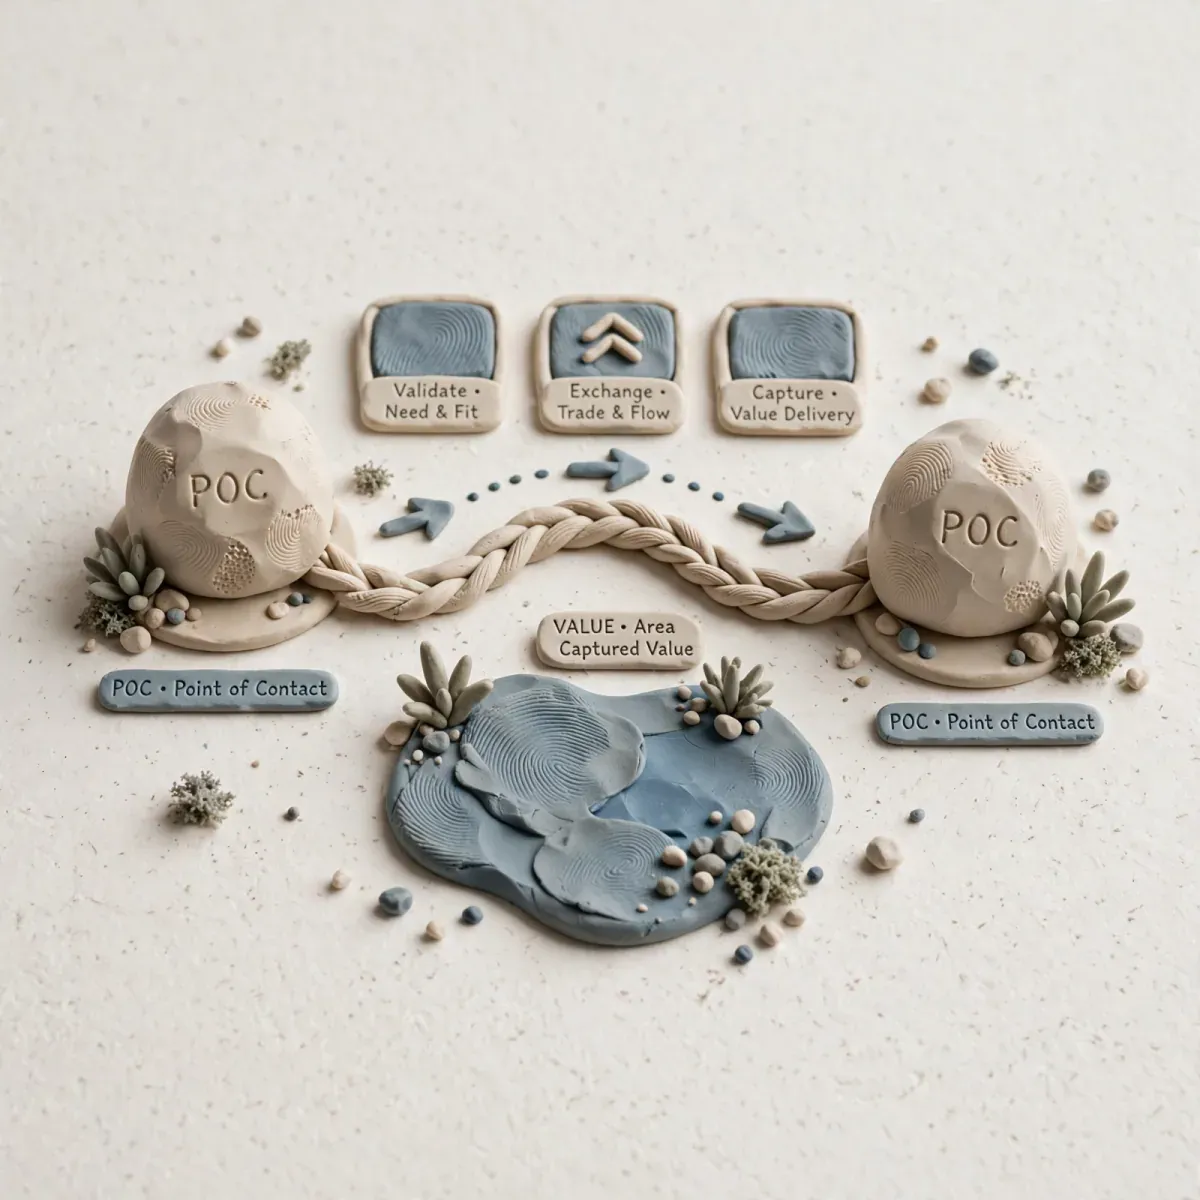
POCs are your airports. LVNs are turbulence. The Value Area is the landing zone. Your job is not to know whether it will fly, but to know what to do when it lands.
Philosophy: From POC to POC
The market spends 70% of its time building value and 30% moving between values. POC-to-POC strategies exploit the latter.
The base idea:
- Find two significant POCs (e.g. yesterday’s and today’s, weekly and daily, monthly and daily).
- Between them there is usually an LVN - a void that price crosses quickly.
- When price leaves one POC/HVN and you have confirmation of aggression (imbalance, delta) and of liquidity defence (Bookmap), you join the move toward the next POC.
- First target: the opposite HVN/POC. Do not try to play further without new acceptance.
Model:
POC_Source (start) -> LVN (fast transport) -> POC_Target (target)

POC_Source = the level from which price left with volume acceptance outside Value
LVN = an area of <30% of average volume per level
POC_Target = Naked POC, weekly POC, VAH/VAL
3 Measurable Strategies
Strategy 1: Mean Reversion to POC (Rotation within Value)
Conditions:
- Day classified as Normal/Neutral (IB 40-60% ATR, no strong extension).
- Price outside the POC, but inside yesterday’s + today’s Value Area (rotation).
- At the edge of the VA (VAH/VAL) you see: absorption + delta exhaustion + a stack on Bookmap.
Entry:
- Return inside the VA + imbalance toward the POC on the 5M footprint.
Stop:
- Behind the Poor High/Low or behind the liquidity wall + 1 ATR M5 as a buffer.
Target:
- POC of the day (first target, 60% of the position), then the opposite VAH/VAL.
EV for mean reversion:
MR WinRate on Normal days ~ 58-62%
Avg Win = distance VAL->POC ~ 0.5 * VA Height
Avg Loss = distance VAL -> Stop (Poor High + ATR)

EV = WR * AvgWin - (1-WR)*AvgLoss
If EV < 0 -> you do not trade, because the VA is too narrow.
Strategy 2: Breakout from Initial Balance to a New Value (Value Discovery)
Conditions:
- Small IB (<35% ATR20), balanced TPO profile in the IB.
- Volume in the IB < 80% of the 20-day average at that time (accumulation before the move).
- IB breakout on: RVOL >1.5 + Delta Efficiency >0.25 + transaction volume outside the IB >150% of the volume in the IB.
Entry:
- Retest of the IB High/Low after the breakout (you do not chase the breakout at market) + the footprint shows no absorption on the opposite side.
Stop:
- Back inside the IB, behind 50% of the IB Range.
Target:
- Measurement: IB Range * 1.5 to 2.0 as the extent, but the real target is the first historical HVN / Naked POC in the direction of the breakout.
- Close the position when absorption + CVD divergence appears at a new high.
| Parameter | Measurement |
|---|---|
| Breakout strength filter | RVOL >1.5 and Delta Eff >0.25 |
| False breakout | Breakout on RVOL <0.9 + large absorption on Bookmap |
| Acceptance confirmation | Volume building outside the IB for >30 min and a new mini POC |
Strategy 3: From Naked POC to Naked POC (Value Transfer)
The strongest positional strategy.
Conditions:
- You have a Naked POC from last month/week that has not been tested for >10 sessions.
- Price returns to its vicinity after a trend and builds volume there (acceptance) or rejects it (absorption).
- Additionally: BOTH POCs (source and target) are visible on the composite profile.
Entry:
- After the test of the Naked POC: if absorption + OBI in the DOM >0.3 in the direction of the target POC, enter in the direction of the target POC.
Stop:
- Behind the Naked POC + LVN buffer.
Target:
- The next Naked POC in the direction of the composite’s Value Area.
This is the strategy trading desks use for weekly positioning, not for scalping. It requires patience.
Composite Profile:
Combine 20-60 days into a single volume profile.
Mark the composite POC and the extreme HVNs as transfer targets.
The composite Naked POC = a place the market has not yet returned to in order to finish its business.
Position Management Plan: Scaling by Volume
Instead of a fixed TP, use a volume ladder:
Entry: 100% of the position

TP1: 40% of the position at the first HVN/POC (mean reversion)
  -> move the Stop to breakeven after TP1 is hit

TP2: 30% of the position at the VAH/VAL or a Naked POC
  -> trail behind the previous HVN (not behind price)

TP3: 30% of the position - a runner after acceptance outside Value, closed when:
  - Buy-side or sell-side absorption appears on Bookmap
  - CVD divergence
  - A new POC starts building against you
Why this way? Because in an LVN price travels fast and you do not want to get off too early. In an HVN price slows down and you want to take profit. The ladder follows the logic of volume, not a rigid RR.
When the Plan Says Do Not Trade
- When the source and target POCs are <0.6 ATR apart. The profit does not cover transaction costs and the risk of slippage in the LVN. Measure the minimum distance:
Distance(POCs) > 1.0 * ATR(20) M30. - When you have 3 or more historical HVNs in the way between the POCs. That is not a clean LVN transfer, but a tug-of-war through 3 parking lots. Every HVN is a risk of a stop. Choose only transfers through at most 1 intermediate HVN.
- When today’s profile is a Double Distribution and you want to play mean reversion to the POC. Your POC is in one of the two distributions, and the second distribution is a separate centre. The market does not have to return to your POC, because it has already built new Value. Plan: play only within your own distribution.
- When the whole week’s CVD goes against your POC-to-POC direction, even though the daily structure looks OK. The weekly transfer beats intraday. If the weekly CVD is falling hard while you want to go long from VAL to POC, you are trading against the flow of large blocks.
- When you have a Poor High/Low as a stopover on the way. The market will most likely test and break the Poor High, which will take out your stop. Avoid routes where there is a Poor High/Low on the way instead of Excess.
Mistakes That Cost the Most
1. Confusing the POC with a magic line and entering without confirmation of aggression and liquidity. The POC alone is just a level. Without the footprint (imbalance), delta (efficiency) and Bookmap (a wall being eaten), it is guessing.
2. No measurement of distance and EV before entering. You go long from VAL to POC when the VA height is 0.2% and the spread plus commission is 0.05%. Your 3:1 RR is an illusion, because the real extent is 0.15% net. Every entry must have a calculation: Net Profit / Net Risk > 1.5.
3. Holding a runner through a Naked POC against you. When price reaches a Naked POC and you see absorption, but you hold because “maybe it will break through”, you give back the entire profit from the transfer. A Naked POC is where the market has the most reasons to turn around.
4. Trading POC to POC on a day when the market is building a new monthly composite. When the monthly profile is building higher and accepting, daily returns to the POC are shallow and short. In such a month the mean reversion strategy has a winrate <45%. Switch to the IB breakout.
5. Using the same IB and POC parameters for all markets. ES has an IB of ~40% ATR, FDAX ~50%, and WIG20 ~60%. An RVOL >1.5 for ES is a strong breakout; for WIG20 you need >2.0 because of lower liquidity. Calibrate each market separately in your journal.
Measurable Exercise - Your POC-to-POC Edge
- Choose one market (e.g. FUS500).
- For 20 sessions, every morning write down:
- POC D, POC W, the nearest Naked POC D and W, VAH/VAL D
- The distances between them in ATR M30
- The previous day’s day type (Normal/Trend/Neutral)
- Each day choose only one route: e.g. VAL D -> POC D, or POC D -> Naked POC W.
- Measure after the fact whether the route was completed (a close beyond the target POC) and how many times there was absorption along the way.
- After 20 days calculate:
- The effectiveness of routes through an LVN (>70% empty space) vs through an HVN
- The average time to travel from POC to POC
- The mean reversion winrate when the open is inside Value vs outside Value
Route journal:
Date | Route (Source->Target) | Distance ATR | LVN % on the route | Previous day type | Reached? (Y/N) | Time | Max DD along the way
After this exercise you will have your own map: which routes work on your market and which are traps.
Check Yourself
- What is a POC-to-POC strategy and why is the LVN key?
- Give the conditions for playing mean reversion to the POC on a Normal day.
- How will you confirm the strength of a breakout from the Initial Balance using RVOL and Delta Efficiency?
- What is a Naked POC and why does it have a higher priority as a target than an ordinary HVN?
- How do you scale your exit by volume (the HVN ladder)?
Frequently Asked Questions
How many POCs should I have on the chart? A maximum of 4: POC D, POC W, POC M and the nearest Naked POC. More is chaos. If you have 10 POCs, you have no plan. Each additional POC lowers the quality of your decisions.
Do POC-to-POC strategies work on stocks? Yes, but on stocks in a monthly trend the monthly POC shifts and the mean reversion method is weaker. On stocks, a breakout from Value to a new Value (strategy 2) and transfers between monthly HVNs work better. On indices and futures all 3 strategies perform comparably.
What timeframe for the entry in a POC-to-POC trade? Analysis: composite profile D/W/M + 30M TPO for the day type. Entry: 5M or 1M Footprint + Bookmap. Never enter on the 30M TPO - that is too big a stop. Precision comes from the 5M footprint at a level from the Volume Profile.
What if price does not reach the target POC and turns back halfway through the LVN? That is information: new acceptance appeared along the way and a new mini POC is building. Your route has become outdated. Close the position at breakeven or a small profit and map the route again. Do not hold in the hope that “it will still get there”.
How do I calculate the EV for my route? Formula:
EV = (WinRate * AvgWin) - (LossRate * AvgLoss)
WinRate = your historical effectiveness for this route type (e.g. VAL->POC on a Normal Day)
AvgWin = distance from entry to TP1 * % of position + TP2 * % + TP3 estimated
AvgLoss = distance from entry to Stop

If EV after costs < 0 over 20 attempts, the route has no edge and must be rejected.
Advertisement
Key takeaways
- You have all the building blocks: Volume Profile, TPO, Footprint, Delta, DOM. Now you will combine them into measurable strategies. Professional value trading is not guessing whether price will bounce. It is playing the move statistically from one place where value is built to another.
Structure sources
The material is based on source documents. Variable values — fees, limits, regulatory figures — are worth checking at the source before making a decision.
- Babypips — School of Pipsology — babypips.com
- TradingView — dokumentacja Pine Script
Disclaimer
- Educational material. Not investment advice or a recommendation. Trading involves the risk of losing capital.
- The materials are educational. They are not investment advice or a recommendation within the meaning of financial instruments trading regulations. Numbers in examples are illustrative unless a measurement date and source are given.
Who writes this and how we check it
The materials are written and verified by Redakcja Kurs Tradera — the rules are described on about the site: every number has a source, and we show gaps openly. Report a factual error via contact — corrections are described in the content.
Progress is stored only in this browser (localStorage) — there is no account and no copy on the server. Clearing site data will remove it. Manage your data