Module 1 / 2
Stop-loss and R-multiple: how to calculate 1R
Stop-loss is placed from chart structure, not from a fixed pip count. Learn to calculate 1R, choose position size, and compare trades in R-multiple.
- Author
- Zordon Intelligence Sp. z o.o.
- Updated
- 15 min read
- Structure sources
- 3
Stop-loss and R-multiple: what you are actually measuring
This lesson explains how to place a stop-loss from chart structure and how to score every trade in R-multiple. It is useful if you already know the 1–2 per cent risk rule but still describe your trades in profit currency instead of relating the result to the risk taken. After reading, you will be able to calculate 1R for any instrument, derive position size from stop distance, and compare two different setups with one number.
What is 1R and how to calculate it
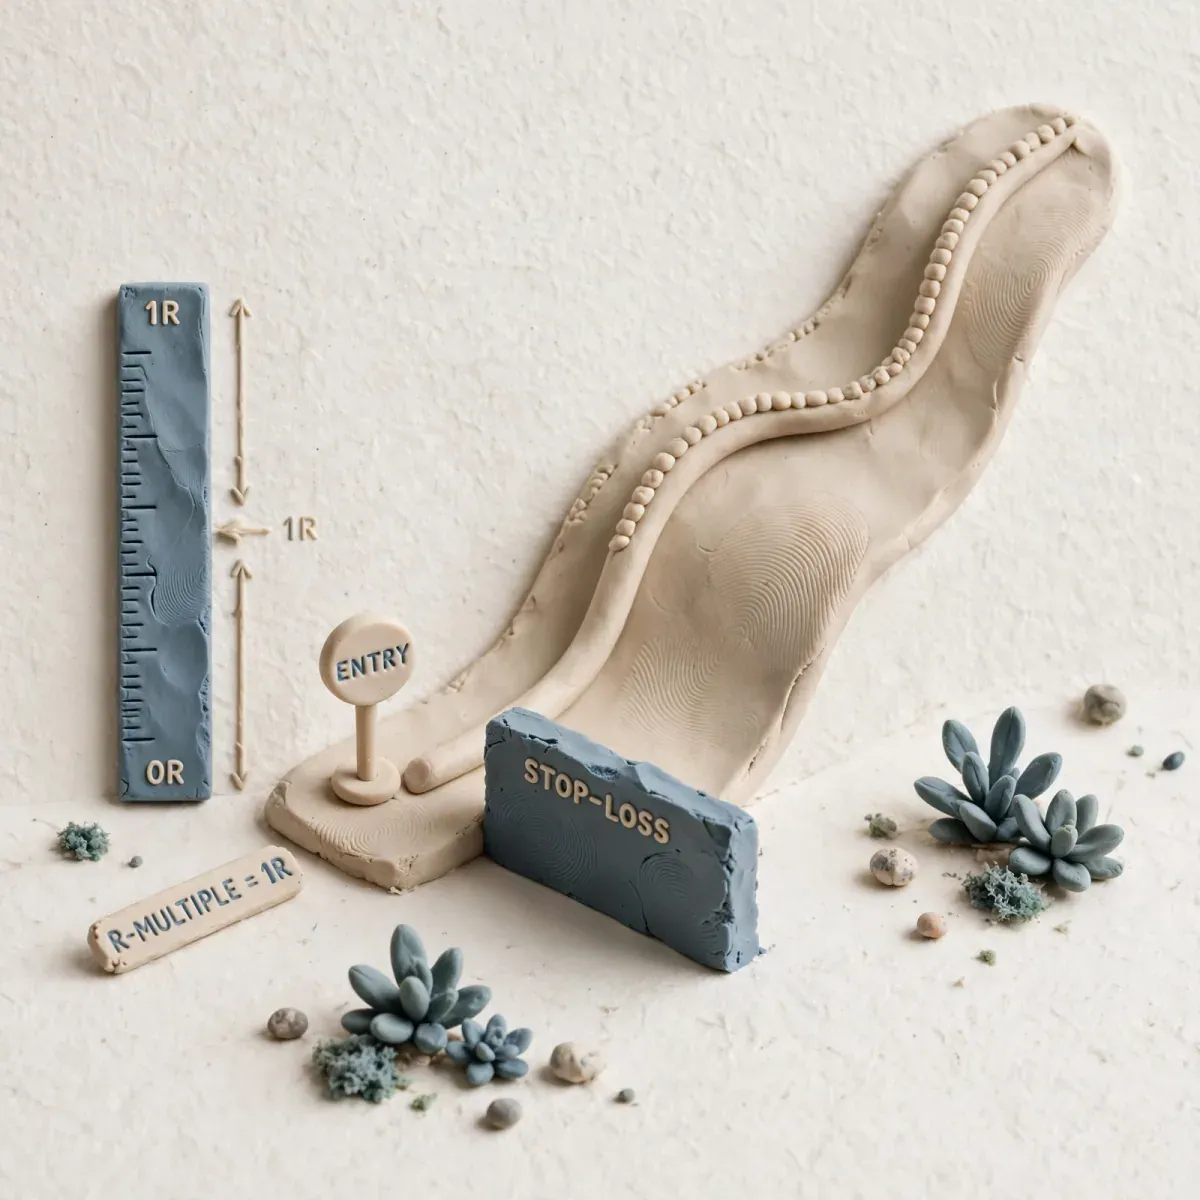
1R is the amount you risk on a single trade. It comes directly from the stop-loss level, converted into account currency. With a capital of 10,000 units and a 1 per cent risk per trade, 1R equals 100 units. The concept is also described in the glossary under R-multiple, and the lesson on the 1–2 per cent risk rule explains how to set per-trade risk.
The basic formula is:
1R in account currency = |entry price - stop price| x position size x point value
Point value depends on the instrument. For stocks, it is usually 1 unit of currency per 1 unit of price movement. For CFDs and futures, you must read it from the instrument specification. Without that number, 1R remains meaningless. You can perform the same calculation in an R-multiple calculator.
| Result | Meaning | Example with 1R = 100 units |
|---|---|---|
| -1R | stop hit as planned | -100 units |
| -0.5R | earlier exit before stop | -50 units |
| 0R | breakeven after costs | around 0 units |
| +1R | profit equal to risk | +100 units |
| +2R | profit twice the risk | +200 units |
| +3R | profit three times the risk | +300 units |
Why measure results in R instead of currency
A journal kept only in currency mixes two different things: account size and decision quality. A profit of 400 units looks the same on a 5,000-unit account and on a 200,000-unit account, but it means something completely different — in the first case it is 8 per cent of capital, in the second 0.2 per cent. Recording in R is comparable regardless of capital: 400 units with 1R = 100 units is always +4R, while with 1R = 800 units it is only +0.5R.
The second benefit is statistical. Without a common unit, you cannot calculate the expectancy of a setup or compare two strategies, because win rate alone without average win size is only half the information. The third benefit concerns execution: spread, commission, and slippage can all be expressed as a fraction of R, and then you can see whether a setup survives costs at all.
Stop-loss from chart structure, not from a fixed pip count
Order matters. First you decide where the investment thesis stops being valid, and only then do you choose position size. The reverse order — I want two lots, so I will place the stop 20 pips away — produces a stop that has nothing to do with the chart.
Four rules for placing stops:
- Beyond the level, not on the level. A stop for an entry on a support bounce belongs below support, not exactly at its price. The level where most orders sit is the level from which price most often bounces back.
- Buffer for noise. Add a margin to the structural level that matches the typical volatility of the instrument — in a calm market a fraction of the average candle range is enough, while a violent market needs more. The buffer protects against random whipsaws, not against a real trend change.
- Outside the high-liquidity zone. A stop inside a tight range collects moves that do not invalidate the setup.
- One stop, one definition. Use the same stop type throughout your journal. If you use a hard stop once and a mental stop the next time, results in R are no longer comparable.
| Stop type | How it works | When it makes sense | Limitation |
|---|---|---|---|
| Hard | stop order sent to the broker system | default choice for most plans | gaps, slippage, and weekends are not excluded |
| Mental | manual exit when price reaches a level | only with proven process repeatability | easy to move under pressure |
| Time-based | exit after a fixed number of candles without movement in your favour | breakout setups that must work immediately | requires a separate rule in the plan |
| Volatility-based | stop distance calculated from current volatility | markets with variable variance, such as around macro data | requires position size recalculation after every volatility change |
Protocol: from invalidation to position size
Seven steps you can repeat for any instrument:
- Write the setup thesis in one sentence: what must happen for the trade to work.
- Point to the level whose breakout invalidates the thesis. Not approximately, but a concrete structural price.
- Add a buffer based on volatility and record the stop price.
- Measure the distance from planned entry to stop in price units.
- Set 1R in account currency: capital multiplied by risk percentage per trade.
- Calculate position size from the formula below and round down, never up.
- Check that the rounded size does not break the risk rule. If it does, skip the setup or look for an entry closer to invalidation.
Position size = (capital x risk percentage) / (|entry - stop| x point value)
Numeric example: capital 20,000 units, 1 per cent risk per trade, so 200 units. Entry at 100.00, invalidation at 97.80, buffer 0.20, stop at 97.60. Distance is 2.40 units per share, so position size is 200 / 2.40 = 83.3, rounded down to 83 units. Actual 1R is 83 x 2.40 = 199.20 units, slightly below the planned 200. Rounding down is intentional: risking 0.996 per cent of capital is safer than 1.008 per cent, which rounding up to 84 units would produce.
If you chose position size first and then searched for a stop, the same calculation would produce a different exit price and most likely land inside the structure. The step order is therefore part of the method, not a matter of convenience.
R-multiple across three trades
After closing a position, the result in R is one division:
result in R = net result in account currency / planned 1R in account currency
| Trade | Entry | Stop | Exit | Net result | Result in R |
|---|---|---|---|---|---|
| A (illustrative) | 100.00 | 97.60 | 107.20 | +600 units | +3R |
| B (illustrative) | 50.00 | 48.00 | 46.00 | -400 units | -2R |
| C (illustrative) | 200.00 | 196.00 | 198.00 | -100 units | -0.5R |
With 1R = 200 units, these three trades average +0.17R. That number must not be interpreted as a system result: three trades are noise, not a strategy outcome. Evaluating a setup requires a sample of dozens of signals, and the lesson on expectancy and drawdown explains how to count them.
Note trade C. Exiting before the stop gave -0.5R, a loss smaller than planned. That result is acceptable only when it follows a rule written down in advance — for example, exiting after losing structure on a lower timeframe. If it is a reaction to anxiety, it cannot be repeated, and therefore it cannot be measured.
Execution costs expressed in R
Cost is not a separate category settled at the end of the month — it is part of every trade result and should be converted the same way as profit:
cost in R = opening and closing cost in account currency / 1R in account currency
Example: spread costs 8 units, commission 4 units, total 12 units for a full round trip. With 1R = 200 units, the cost is 0.06R. Individually it looks innocent, but twenty such trades cost 1.2R, more than one full winning trade at 1R. With 1R = 100 units, the same cost becomes 0.12R per trade.
On top of that comes slippage on stops. A stop order becomes a market order, so execution is often worse than the price you saw on the chart. If average slippage on stops is 0.05R, one hundred trades cost an extra 5R.
The practical conclusion is simple: as long as costs are not expressed in R, you do not know whether your setup has an edge or only promises one. The lesson on round-trip cost explains how to measure full execution cost, and the slippage glossary entry explains the difference between order price and fill price.
Breakeven exit, partial close, and trailing stop
Three techniques that most often break the R accounting because they change the system during the trade:
- Moving stop to entry price. It makes sense only when a rule says when to do it — for example, after reaching +1R. Without a decision threshold, it is a reaction to price movement, not a plan.
- Partial close. Closing half the position at +1R and moving stop to zero reduces result variance, but it also lowers the average win in R. This change must be built into expectancy; otherwise, you are measuring a system you do not actually trade. Gradually increasing position size after confirmation is covered in the lesson on scaling position size.
- Trailing stop. The rule must be mechanical: below the last confirmed swing low on the chosen timeframe, or by a fixed multiple of volatility. Moving the stop because the price is moving in your favour is a different system for every trade.
The sentence worth remembering: if position management was not written down before entry, it is not part of the setup.
When the chart says do not trade
Four conditions after which a trade should not be created, even with a valid entry signal:
- You cannot identify an invalidation level. If the stop is arbitrary, there is no 1R — there is only a position without an exit plan.
- The required position size drops below the account minimum. With small capital and a wide stop, the minimum lot breaks the risk rule. In that case, skip the setup instead of squeezing the stop.
- The stop sits inside the noise zone. If the nearest sensible invalidation is closer than the typical candle volatility, every twitch will stop you out before the thesis plays out. The criteria for declaring a signal complete are covered in the lesson on setup definition.
- You have to move the stop for the position to fit. That is a sign that you are matching position size to emotion instead of to capital.
Worksheet: ten trades in R
First write down your own rules so that you have something against which to compare results later:
| Element | Your rule | | --- | --- | --- | | Stop type (hard, time-based, trailing) | | | How you define the invalidation level | | | Noise buffer | | | Rule for moving stop to breakeven | | | Rule for partial close | |
Then fill in the sheet after each trade. Fill in the plan-compliant column immediately, not a week later.
| # | Date | Setup | Planned 1R | Net result | Result in R | Cost in R | Plan compliant |
|---|---|---|---|---|---|---|---|
| 1 | |||||||
| 2 | |||||||
| 3 | |||||||
| 4 | |||||||
| 5 | |||||||
| 6 | |||||||
| 7 | |||||||
| 8 | |||||||
| 9 | |||||||
| 10 |
After ten rows, calculate three numbers:
average R = sum of results in R / number of trades plan compliance rate = plan-compliant rows / number of trades x 100 average cost in R = sum of costs in R / number of trades
If average cost exceeds 0.2R, improve execution and instrument selection before looking for a new setup. Adding indicators to a system that gives away edge on spread does not solve the problem.
Common stop-loss mistakes
- Placing the stop below a round number because everyone else has stops there. The visible level is where orders cluster, not where invalidation lies.
- Fitting the stop to a desired risk-reward ratio. If the stop does not fit the natural structure, the problem is the entry point, not the reward.
- Skipping the stop because of experience. Tenure does not change the fact that a position without a defined exit has no measurable risk.
- Using different stop definitions in the same journal. Once a hard stop, once a mental stop, without marking the difference — comparing results in R then becomes meaningless.
- Treating 1R as a fixed currency amount. 1R changes with capital. After a series of wins, you must recalculate position size so that the percentage risk stays the same.
Measurable exercise
- Choose one instrument and write down three numbers: capital, risk percentage per trade, and 1R in account currency.
- For the last ten signals — they may come from a demo account — record the invalidation level, the position size from the formula, and the result the chart-based stop would have given.
- Fill in both sheets above and calculate average R, plan compliance rate, and average cost in R.
- Write one change to your plan, for example a rule for moving stop to breakeven, and date the version.
Without this sheet, you do not know whether you are improving the setup or just the story about it.
What does a result of +2R mean at a risk of 80 units?
+2R is twice the risk: 2 × 80 = 160 units before any tax. The result in R describes the relation to the risk taken, not the size of leverage.
Common questions
Does a stop-loss always have to give exactly −1R?
You plan 1R as a full invalidation. An earlier exit can give −0.5R and is fine if it comes from a rule rather than from panic. Mark the reason for such an exit in the journal so it can be counted together with the rest.
How do I count R with partial closes?
Add up the net result of the whole position and divide it by the original risk in account currency. One trade gets one R number, and describe how the position was split in a note next to it.
Is a 1:2 reward-to-risk ratio mandatory?
No. What counts is expectancy, i.e. win rate multiplied by average win in R minus loss rate multiplied by average loss in R, after costs. A 1:2 ratio is a common starting point, not a necessary condition.
Why measure the result in R rather than in account currency?
Because only a common unit lets you compare trades of different sizes and calculate the expectancy of a setup. An amount in account currency depends on account size, so the same 400 unit profit describes 8 percent of capital in one case and 0.2 percent in another. Without R you cannot tell a system improvement from a change in position size.
Advertisement
Key takeaways
- Stop-loss belongs where the thesis stops being valid, not where a round pip number looks neat. 1R is the risk amount per trade, and R-multiple is the result divided by that risk. Position size is calculated from stop distance and capital, never the reverse. Execution costs expressed in R show how much spread eats from the setup.
Structure sources
The material is based on source documents. Variable values — fees, limits, regulatory figures — are worth checking at the source before making a decision.
- Babypips — risk management / position sizing — babypips.com
- StockCharts ChartSchool — trading psychology & risk concepts — chartschool.stockcharts.com
- KNF — investor education — knf.gov.pl
Disclaimer
- Educational material. Not investment advice or a recommendation. Trading involves the risk of losing capital.
- The materials are educational. They are not investment advice or a recommendation within the meaning of financial instruments trading regulations. Numbers in examples are illustrative unless a measurement date and source are given.
Who writes this and how we check it
The materials are written and verified by Redakcja Kurs Tradera — the rules are described on about the site: every number has a source, and we show gaps openly. Report a factual error via contact — corrections are described in the content.
Progress is stored only in this browser (localStorage) — there is no account and no copy on the server. Clearing site data will remove it. Manage your data