Module 1 / 2
FOMO, revenge trading, overtrading - STOP protocols
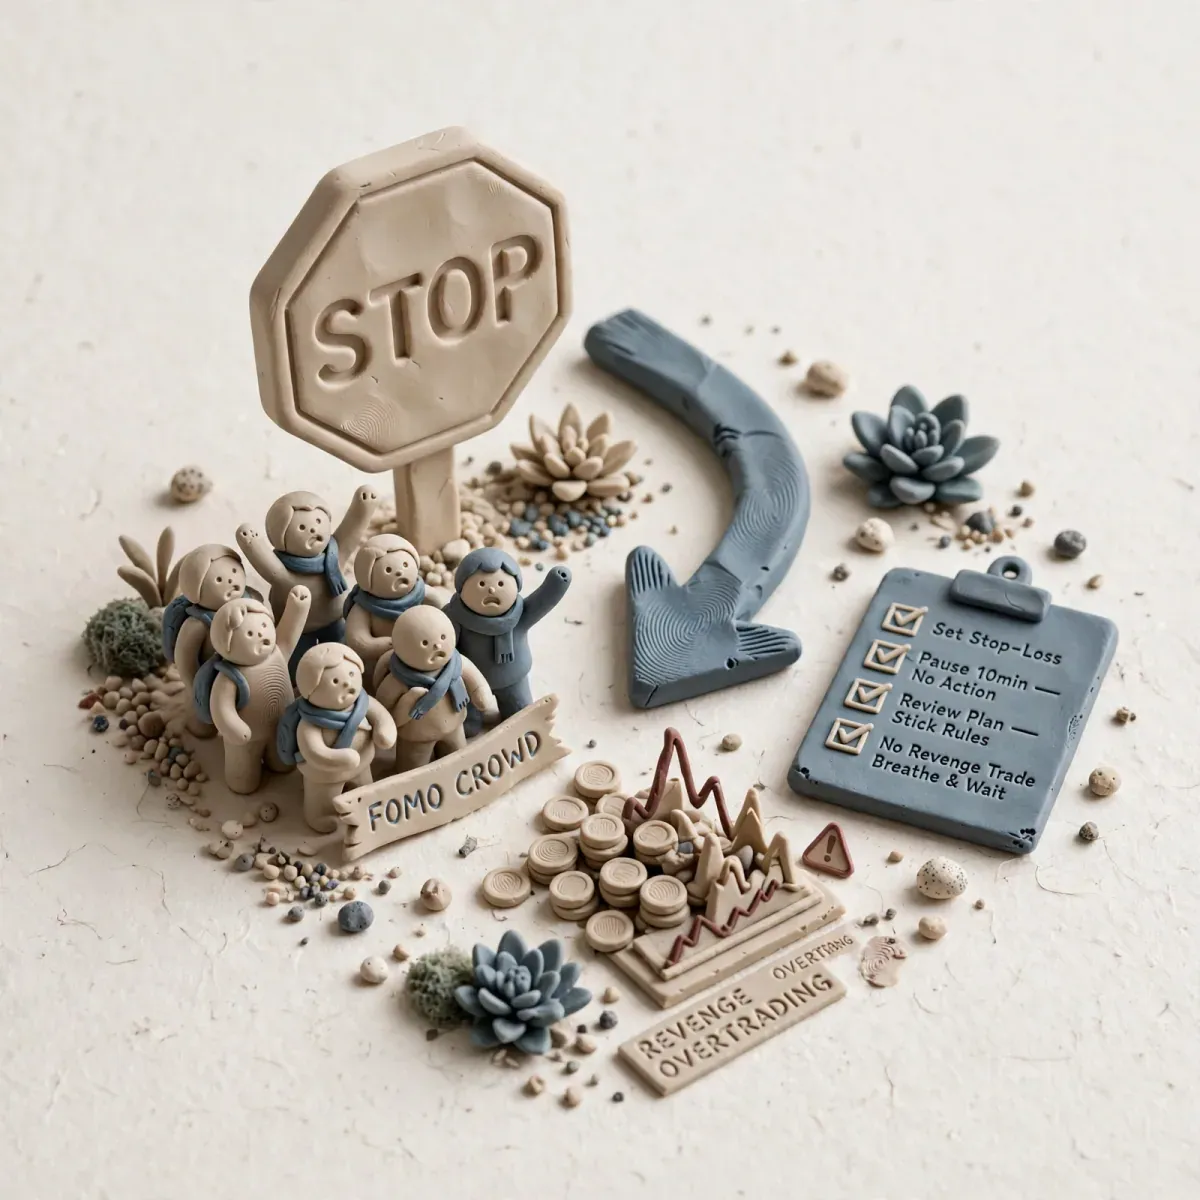
90% of retail trader losses do not come from a bad system. They come from three behaviour patterns: FOMO (entering because it is running away), revenge trading (entering to win it back) and overtrading (entering because of boredom / the need for action). Each of them has a different neurobiology, but the same effect:...
- Author
- Zordon Intelligence Sp. z o.o.
- Updated
- 9 min read
- Structure sources
- 2
90% of retail trader losses do not come from a bad system. They come from three behaviour patterns: FOMO (entering because it is running away), revenge trading (entering to win it back) and overtrading (entering because of boredom / the need for action). Each of them has a different neurobiology, but the same effect: executing trades outside the plan with negative expectancy. This lesson takes them apart and gives you STOP protocols.
The anatomy of three account killers
All three patterns are attempts to regulate emotion through action in the market, instead of through the body or the plan.
| Pattern | Source emotion | Automatic thought | Behaviour goal | Real cost |
|---|---|---|---|---|
| FOMO | Fear of missing out, regret | “It is running away, last chance, they will make money without me” | Reduce the tension of not being in | Entry at the top, no edge, -1R |
| Revenge trading | Anger, a sense of unfairness, shame | “The market took from me, I have to get it back, I cannot end the day like this” | Restore status / control | Increasing lot size, no stop, -2R to -5R |
| Overtrading | Boredom, restlessness, need for dopamine | “I have to do something, sitting here is a waste of time” | Deliver stimulation | Multiplying transaction costs, blurred focus, -0.3R x 10 |
The common denominator: the trade is not a response to the market. It is a response to an internal state.
The formula for the true cost of an impulsive trade:
Cost_FOMO_Revenge = Loss_R + Opportunity_Cost + Psychological_Cost

Where:
Loss_R = e.g. -1.2R
Opportunity_Cost = A plan-compliant setup you did not take because you were in a bad position = e.g. +2R forgone
Psychological_Cost = A higher Tilt_Score tomorrow, lower trust in yourself = +1 to Tilt_Risk_Score

Total cost of 1 impulse = -1.2R - 2R + poor execution tomorrow
That is why professionals count not only P&L, but the % of planned versus impulsive trades.
FOMO - detection and STOP protocol
FOMO has a very distinctive signature:
Physiological signature: tension in the chest, shallow breathing, the compulsion to look at the chart every 10 seconds, your hand on the mouse.
Cognitive signature:
- Comparing yourself to others (“others have already made money”)
- Black-and-white thinking (“either now or never”)
- Expanding the definition of the setup (“well, it almost meets the conditions”)
FOMO-STOP protocol (90 seconds):
F - FREEZE: Stop physically. Move your hands away from the keyboard/mouse. 5 seconds without movement.
O - BREATHE: 3 cycles of physiological breathing: 2x inhale through the nose (short + long), long exhale through the mouth >6s
M - MEASURE: Ask 3 questions out loud:
  1. Is this setup A/B/C from my plan? YES/NO
  2. Are my stop and size defined before entry? YES/NO
  3. If this candle were red instead of green, would I still want to enter? YES/NO
O - DESCRIBE: Write one sentence: "I feel FOMO because ___ (e.g. BTC rose 5% without me). My body feels ___"
S - STOP or SYSTEM: If any MEASURE = NO -> STOP, close the chart for 15 min. If 3x YES -> Enter ONLY according to the plan, at 50% size.
The 50% size rule: If you enter after a FOMO signal, but the setup genuinely meets the plan, your brain is already in a state of elevated dopamine. Your objective assessment of risk is impaired. Smaller size = less impact from the cognitive error.
Revenge trading - the most expensive pattern
Revenge trading is an attempt to rewind time. The loss has already happened. The brain does not want to book it as a “business cost”. It wants to cancel it.
From the trader journals we analyse at KursTradera: the average revenge loss is 2.8x larger than the average planned loss. And 73% of revenge trades end in a loss larger than the original loss that triggered them.
| Revenge phase | What the trader does | What the plan says |
|---|---|---|
| 1. Denial | “This could not have happened, it is manipulation” | The loss is a cost. We book it. |
| 2. Anger | Doubles the lot 2x, 3x, enters without a stop | Size defined before the session |
| 3. Bargaining | Moves the stop, averages down the loss | The stop is non-negotiable |
| 4. Chase | Enters another market “to make it back” | One market, one plan at a time |
REVENGE-STOP protocol (Hard Circuit Breaker):
RULE -2R: Daily loss limit = -2R MAX. After reaching -2R:
  1. Close the platform. Literally. ALT+F4 / CMD+Q.
  2. Start a 60-minute timer. No looking at the chart.
  3. Do a physical reset: 20 push-ups / a 10-min walk / a cold face rinse.
  4. Only after 60 min open the journal and describe the sequence. Zero trading until the end of the day.

RULE 3 LOSSES IN A ROW (if each >= -1R):
  - A 30-min break + reduce size by 50% until the end of the day.
  - Ask the question: Does the market today meet the conditions for my system? If NOT - the day is over.

ANGER RULE:
  If you feel anger >6/10 (scale 1-10) - no increasing size. Base size or smaller only.
Journal formula:
Revenge_Ratio = Sum_of_revenge_losses / Sum_of_all_losses

Target: <15%
Alert: >30% - the anti-tilt system is not working, go back to Lesson 04

Revenge_After_Loss = % of days when a trade <30 min after a loss >1R happened

Target: <10%
Overtrading - the quiet killer through costs
Overtrading rarely looks dramatic. It is not -5R in one trade. It is 12 entries at -0.2R, +0.1R, -0.3R… At the end of the day -1.5R from commissions and spread alone, and no energy left for a real setup.
Diagnosing overtrading is simple:
| Metric | Formula | Healthy level | Overtrading |
|---|---|---|---|
| Trades per day | Number of trades / day | Defined in the plan (e.g. 1-3) | >150% of plan for 3 days in a row |
| Plan adherence | Plan-compliant trades / all trades | >85% | <70% |
| Cost drag | (Commissions+swap) / Capital | <0.5% per day | >1% per day |
| Screen time without a setup | Hours of staring | <2h | >4h |
OVER-STOP protocol:
1. DEFINE MAX TRADES: In your plan write MAX 3 trades per day (for example). After 3 - done, even if "there is an opportunity". The fourth opportunity belongs to tomorrow's you.

2. DEFINE TRADING WINDOWS: e.g. 9:00-11:00 and 15:30-17:00. Outside those windows the chart is closed. Boredom is not a reason to trade.

3. BOREDOM CHECKLIST (when you feel the urge to click without a setup):
   - Have I eaten, drunk water, taken a 2-min break from the screen in the last hour?
   - Have I done 10 squats?
   - Have I read my plan out loud?
   If not - do it before you click.

4. DRAFT RULE: Do you feel like a trade outside the plan? Write it on a piece of paper with the entry price and the stop. Do not click. Check the result after 2h. In 80% of cases you will be grateful you did not click. Track your draft statistic.
When the plan says: do not trade
- When in the last 30 minutes you had a trade that broke 2 or 3 of the FOMO-STOP MEASURE questions. That means your filter is no longer working. Every subsequent trade has a >70% chance of being impulsive. Close the platform for 30 minutes. Measurement > emotion.
- When you enter “making-it-back mode” - counting in your head how much you need to earn to break even today. This is the definition of revenge. When your thoughts are about today’s P&L instead of executing the plan, the plan says STOP. Daily P&L is an outcome, not an intraday goal.
- When you have already made the maximum number of trades from the plan (e.g. 3) and you feel like “just one more”. Overtrading starts after the limit is exhausted. Limits exist to protect you from yourself when your resources are low. Breaking the limit once teaches your brain that limits are negotiable.
Mistakes that cost the most
Mistake 1: No pre-defined daily loss limit (-2R) and trade count. Without a limit there is no circuit breaker. Without a circuit breaker one emotional sequence can wipe out a week or a month. Professional prop firms remove traders for breaking the limit not because they are strict, but because the statistics are brutal: a trader at -3R in tilt averages -5.5R by the end of the day.
Mistake 2: Treating the STOP protocols as “suggestions” rather than as code you execute like an algorithm. A protocol only works when it is automatic. If at the moment of FOMO you start arguing with the protocol (“but this time it really looks good”), the protocol does not exist. Write it on a card next to your monitor. Execute it step by step. Do not negotiate with a safety procedure.
Mistake 3: Measuring only P&L instead of Revenge_Ratio and Plan Adherence. P&L lies in the short term. You can be +3R from 5 revenge trades and think you are a master. In two weeks you will give back +8R. What you measure grows. If you measure only profits, ignorance of risk grows. Measure the % of planned trades.
Measurable exercise
Goal: Reduce the number of impulsive trades by 50% in 14 days and introduce limits.
Steps:
- Define in your plan file:
MAX_LOSS_DAY = -2R MAX_TRADES_DAY = 3 MAX_IMPULSIVE_WEEK = 2 - Over 10 sessions keep a table:
| Date | Number of trades | Plan-compliant | Impulsive (FOMO/R/O) | Daily loss R | Was the limit broken? | Was a STOP protocol applied? |
|---|
- Every day calculate:
Plan_Adherence = Compliant / All * 100%
Impulsive_Rate = Impulsive / All * 100%- After 10 sessions calculate: is Impulsive_Rate falling? Do the days with a STOP protocol applied have a smaller loss than the days without?
Pass criterion: 10 days of data, Plan_Adherence >=80% in the last 5 days and zero days with MAX_LOSS_DAY exceeded.
Check yourself
- Explain the difference in source emotion and automatic thought between FOMO, revenge trading and overtrading.
- Give the formula for the total cost of an impulsive trade (not only Loss_R). Why is the opportunity cost often larger than the loss?
- Run the FOMO-STOP protocol on an example: BTC rises 6% in 20 min, you have no position, you feel a sting. What do you do step by step?
- What is the average loss statistic for revenge versus a planned loss according to the data in this lesson? What % of revenge trades end in a larger loss than the trigger?
- Define the 4 metrics for diagnosing overtrading and give the alert thresholds.
Frequently asked questions
Is FOMO always bad? Sometimes “it runs away” and it is right. FOMO is not a market forecast. It is a state of your nervous system. The market sometimes keeps going without you - that is normal. Your edge is not catching every move, it is repeatedly executing setups with positive expectancy. If there was no setup, it was not your trade, even if it went +5R. Keep a journal of missed opportunities - how many moves “without you” actually met your plan? Usually <20%.
What if I really have to make back a loss, because my capital is small? Financial pressure is fuel for revenge. The maths is relentless: trying to make it back with increased size under elevated stress has negative expectancy and increases the risk of ruin exponentially. The solution is not a larger lot, it is a smaller one and a longer horizon. If the capital is too small to accept -2R without pressure, the position is too big.
How do I tell overtrading from an active scalping strategy? Scalping has a defined plan: how many trades, at what hours, which setup, what maximum cost. Overtrading has no plan, or routinely exceeds the plan. Measure Plan Adherence. A scalper with a plan of 15 trades a day and 90% adherence is not an overtrader. A trader with a plan of 3 trades and 8 executed per day is an overtrader, even if those 8 were profitable.
Advertisement
Key takeaways
- 90% of retail trader losses do not come from a bad system. They come from three behaviour patterns: FOMO (entering because it is running away), revenge trading (entering to win it back) and overtrading (entering because of boredom / the need for action). Each of them has a different neurobiology, but the same effect:...
Structure sources
The material is based on source documents. Variable values — fees, limits, regulatory figures — are worth checking at the source before making a decision.
- Mark Douglas — "Trading in the Zone"
- Brett Steenbarger — "The Psychology of Trading"
Disclaimer
- Educational material. Not investment advice or a recommendation. Trading involves the risk of losing capital.
- The materials are educational. They are not investment advice or a recommendation within the meaning of financial instruments trading regulations. Numbers in examples are illustrative unless a measurement date and source are given.
Who writes this and how we check it
The materials are written and verified by Redakcja Kurs Tradera — the rules are described on about the site: every number has a source, and we show gaps openly. Report a factual error via contact — corrections are described in the content.
Progress is stored only in this browser (localStorage) — there is no account and no copy on the server. Clearing site data will remove it. Manage your data