Module 1 / 2
Tokenomics – vesting, inflation, unlocks
A token's price is a function of demand and supply. Demand is narrative-driven and volatile. Supply is deterministic and written into the contract – you can calculate it down to the day. Yet most traders ignore the unlock schedule, staking inflation and insider allocation, a...
- Author
- Zordon Intelligence Sp. z o.o.
- Updated
- 7 min read
- Structure sources
- 2
Introduction
A token’s price is a function of demand and supply. Demand is narrative-driven and volatile. Supply is deterministic and written into the contract – you can calculate it down to the day. Yet most traders ignore the unlock schedule, staking inflation and insider allocation, and then are surprised why a “good project” falls while TVL rises.
Tokenomics is not a marketing whitepaper. It is supply mechanics. In this lesson you will learn to read vesting, calculate real inflation, assess unlock risk, and build a filter that rules out tokens with toxic supply regardless of the narrative.
Supply fundamentals
Three definitions whose confusion costs money:
| Concept | Definition | Where to check |
|---|---|---|
| Max Supply | The maximum amount that will ever exist (e.g. 1 billion) | Tokenomics docs, CoinGecko |
| Total Supply | The amount already minted, minus burned | On-chain, CoinGecko |
| Circulating Supply | The amount unlocked and in circulation (though not always liquid) | TokenUnlocks, vesting dashboard |
Value metrics based only on Market Cap from Circulating Supply lie. A project can have a $100M Market Cap with 10% of supply in circulation and a $1B FDV (Fully Diluted Valuation).
FDV = Current price * Max Supply
Real Market Cap for valuing the narrative = FDV, not Market Cap
Market Cap / FDV = % of unlocked supply

Example:
Price = $1, Circulating = 100M, Max = 1B
Market Cap = $100M
FDV = $1B
MC/FDV = 10% -> 90% of supply still locked, future supply = 9x current
The lower the MC/FDV, the greater the dilution risk.
Vesting – who gets how much, and when
A standard allocation split:
| Group | Typical range | Vesting period | Risk |
|---|---|---|---|
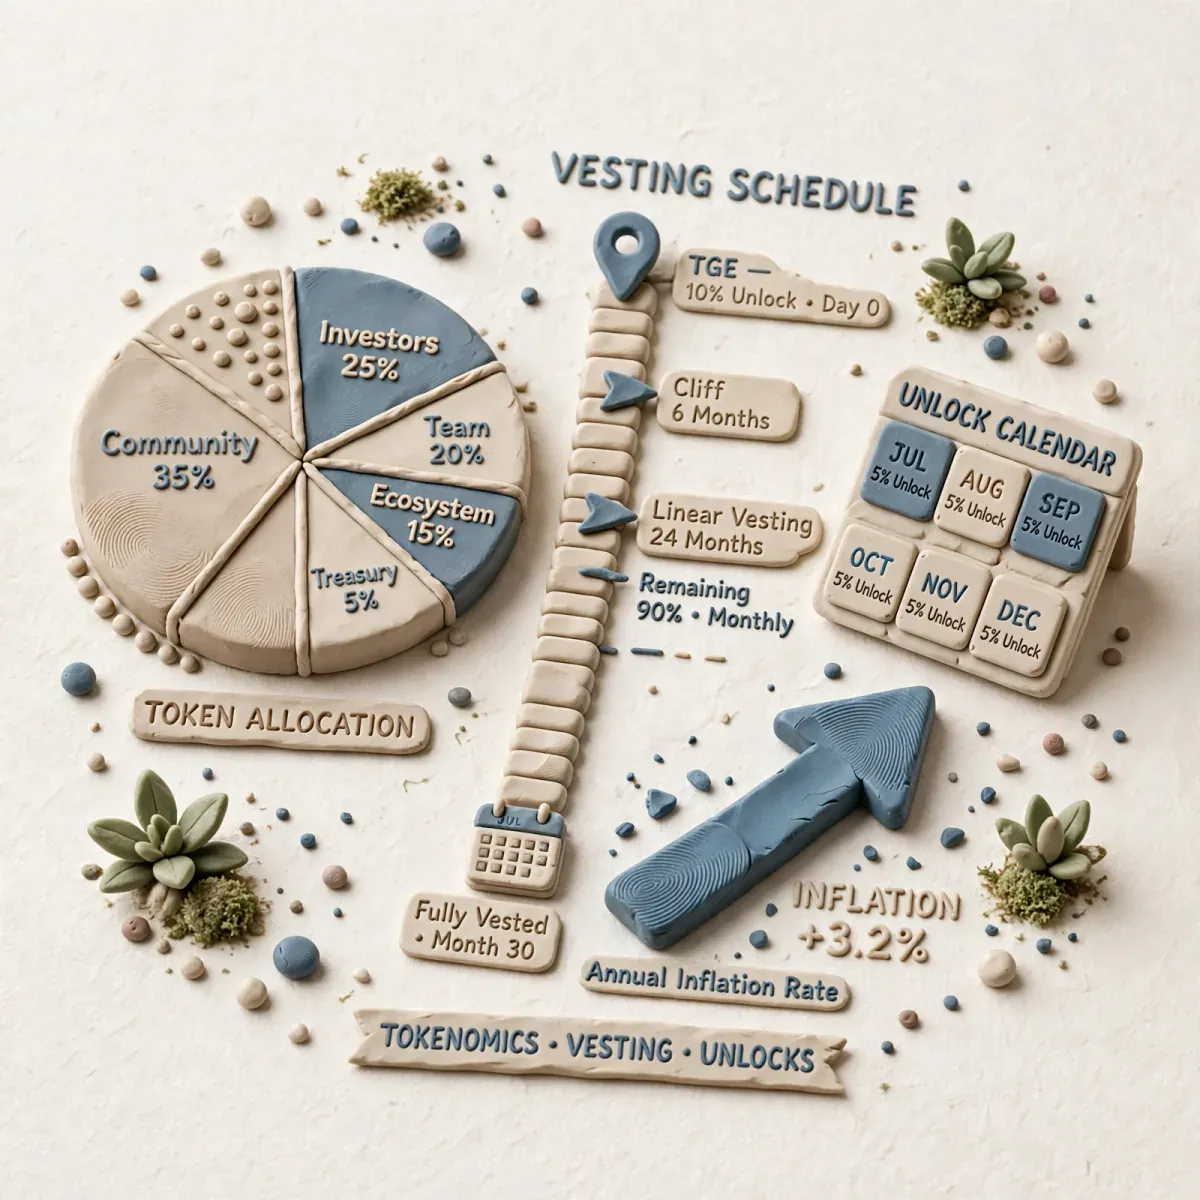
| Team | 10-20% | 0% at TGE, 1-year cliff, 2-3 years linear | Selling after the cliff |
| Investors (VC) | 10-30% | 0-10% at TGE, 1-year cliff, 1-2 years linear | The greatest pressure at unlock |
| Community / Airdrop | 5-20% | A lot at TGE | Short-term pressure |
| Treasury / Ecosystem | 20-50% | Linear over 3-5 years | Hidden supply – the team can sell “for development” |
| Staking Rewards | 10-20% | Continuous emission | Constant inflation |
Two types of vesting:
Cliff = a period with no unlocks, then a large release
Linear = a steady daily / per-block unlock

Example:
Team: 1y cliff + 2y linear = 0% in year 1, then 100% / 730 days = ~0.137% per day for the team pool
Where to check: TokenUnlocks, Tokenomist (formerly TokenUnlocks), the project’s vesting dashboard, the vesting contract on Etherscan (the vestedAmount function).
Inflation – the hidden tax
In crypto we calculate inflation differently than in fiat money supply.
Nominal annual inflation = (New tokens per year from staking emission / inflation) / Circulating Supply

Real inflation for a non-staking holder = Nominal inflation / (1 - % staking)

Example:
Circulating = 100M, staking emission 20M per year, 50% staking
Nominal inflation = 20%
Real for a non-staker = 20% / 0.5 = 40% dilution of purchasing power relative to the staking pool

Staking APR must be > Real inflation for you not to lose
Projects with a high APR (15-30%) often have 20-40% inflation – APR is an illusion if you do not account for dilution. Check the staking ratio and whether the rewards come from inflation or from real yield (fees).
Inflation vs Deflation: models
- Inflationary: ATOM, SOL (until recently), most L1s with validator rewards.
- Disinflationary: BTC – declining emission, ETH after EIP-1559 – deflationary at high usage.
- Burn mechanism: whether the burn is real (from fees) or theatrical (from a small part of emission).
Unlocks – the calendar that kills setups
An unlock does not equal a sale, but it creates the condition for a sale. A large unlock in a quiet market = no demand to absorb it.
Procedure for assessing an unlock:
- Size vs liquidity:
Unlock % of circulatingandUnlock value vs 30d avg volume. If the unlock is >5% of circulating and >50% of daily volume – high risk. - Who receives it: Team/VC = a greater risk of selling than Ecosystem.
- Price vs VC entry cost: If a VC entered at $0.01 and the price is $1, they have 100x. Even 10% of their selling breaks the chart.
- Market context: An unlock on the day of a major narrative (ETF approval) will be absorbed more easily than on a quiet day.
Unlock risk indicator:
Unlock Risk Score = (Unlock value in USD / 30d avg daily volume) * (1 + % VC in the unlock)

>1.0 = high risk, consider no exposure for 3 days before/after
0.5-1.0 = medium, reduce the position
<0.5 = low
Tools: TokenUnlocks calendar, DeFiLlama Unlocks, the Twitter bot @TokenUnlocks.
Case: how to read an unlock in 2 minutes
Project X: MC $200M, FDV $2B, an unlock in 3 days: $30M (15M tokens), of which $20M is for Series A VCs.
- MC/FDV = 10% -> toxically low unlocked supply
- $30M vs Avg Volume $10M = 3x daily volume
- VC cost $0.05, price $2 = 40x unrealized – motivation to realize
- Conclusion: this is not a zone for holding spot unhedged; there is downside gap risk.
This is not advice, only a risk framework.
When the plan says do not trade
- When MC/FDV < 15% and an annual cliff is approaching. 85% of supply is still to be unlocked. Even if it looks technically pretty, the supply math is against you long term.
- When the unlock is >100% of average volume and you have no stop plan. Expecting that “the market will absorb it”, without measuring, is gambling.
- When inflation is >25% and the staking ratio is <40%. The market bleeds every day. A 20% APR does not cover the dilution.
- When the tokenomics documentation is not public or the vesting contract cannot be verified on-chain. No transparency = not tradable.
- When the team changes the vesting rules mid-way (re-vesting, delaying an unlock “for the good of the community”). This often means a lack of demand and an attempt to prop up the price. Trust falls.
The mistakes that cost the most
- Using Market Cap instead of FDV for comparisons. Comparing two L2 projects: one with MC $300M and FDV $400M, the other with MC $300M and FDV $4B are two different risk worlds.
- Ignoring investor entry cost. Looking only at the unlock size, without the VC entry price. A $5M unlock for VCs sitting at 50x is more tempting than $20M for a community at 0x.
- Staking a hyperinflationary token “because of the high APR”. You count the profit in token quantity, not in USD. If the token falls 45% and you receive 30% APR in tokens, you are down 15% in USD.
- Treating a fee burn as a guarantee of deflation. Burn only works when network usage is high. In a bear market fees fall, the burn shrinks, and inflation returns.
- Not keeping an unlock calendar for your portfolio. You hold 5 alts and do not know that 3 of them have unlocks this week. Your supply exposure is cumulative.
Measurable exercise
Task – audit 5 tokens you hold or follow:
Create a table:
| Token | Price | MC | FDV | MC/FDV % | Next unlock (date, %) | Who receives it | Annual inflation | Staking ratio | Real APR (APR - real inflation) | Conclusion: HOLD / REDUCE / DO NOT HOLD through the unlock |
Formulas:
Real APR = Nominal APR - (Nominal inflation / (1 - Staking Ratio))
Unlock % = Unlock value / Circulating Mcap
Once filled in, mark the tokens where MC/FDV <20% and Unlock % >5% within 30 days – that is a red flag. After 30 days, measure whether the red-flag tokens performed worse than BTC.
Check yourself
- Calculate FDV for a token: price $0.5, max supply 2B, circulating 300M.
- Why is MC/FDV = 10% riskier than MC/FDV = 70%?
- What is the difference between a cliff and linear vesting?
- How do you calculate real inflation for a holder who does not stake?
- What will you check in 60 seconds before opening a position in an altcoin, from the unlock perspective?
Frequently asked questions
Does a large unlock always mean a drop? No. It means conditional supply. If a project has a major announcement, a CEX listing and an inflow of demand at the same time, the unlock can be absorbed. But TokenUnlocks statistics show that 7 days after a large unlock (>5% circ) the median result vs BTC is negative. Hence a risk plan, not a certainty.
Where do I find the VC entry cost? CryptoRank, Crunchbase, Messari fundraising data, the project’s spreadsheet. Sometimes the project itself publishes the round price. If it does not – that is information.
80% APR on a new chain – should I take it? Do the math. If annual inflation is 120% and the APR comes from inflation, the token must rise for you to be up in USD. Check how much of the APR is real yield (fees) and how much is token printing. On Dune, search for “Real Yield Dashboard”.
Does FDV make sense for memecoins with no unlocks? Yes, but the interpretation is different. For memecoins FDV = MC as a rule (100% unlocked). The risk does not lie in unlocks, only in the concentration of the top 10 holders – check Bubblemaps.
How do I handle unlocks if I want to hold long term? Measure them. If you believe in the project, you can reduce the position before the unlock and buy back after, instead of holding through the uncertainty. Or hedge with perpetual futures, if you have access. Mainly: do not be surprised – the calendar is the foundation.
Advertisement
Key takeaways
- A token's price is a function of demand and supply. Demand is narrative-driven and volatile. Supply is deterministic and written into the contract – you can calculate it down to the day. Yet most traders ignore the unlock schedule, staking inflation and insider allocation, a...
Structure sources
The material is based on source documents. Variable values — fees, limits, regulatory figures — are worth checking at the source before making a decision.
- Glassnode / Nansen — on-chain analytics
- Binance Research — crypto reports
Disclaimer
- Educational material. Not investment advice or a recommendation. Trading involves the risk of losing capital.
- The materials are educational. They are not investment advice or a recommendation within the meaning of financial instruments trading regulations. Numbers in examples are illustrative unless a measurement date and source are given.
Who writes this and how we check it
The materials are written and verified by Redakcja Kurs Tradera — the rules are described on about the site: every number has a source, and we show gaps openly. Report a factual error via contact — corrections are described in the content.
Progress is stored only in this browser (localStorage) — there is no account and no copy on the server. Clearing site data will remove it. Manage your data